Editorial
Developer Default in Thailand: What Happens to Your Money
By THAI.ESTATE Editorial Team12 min read
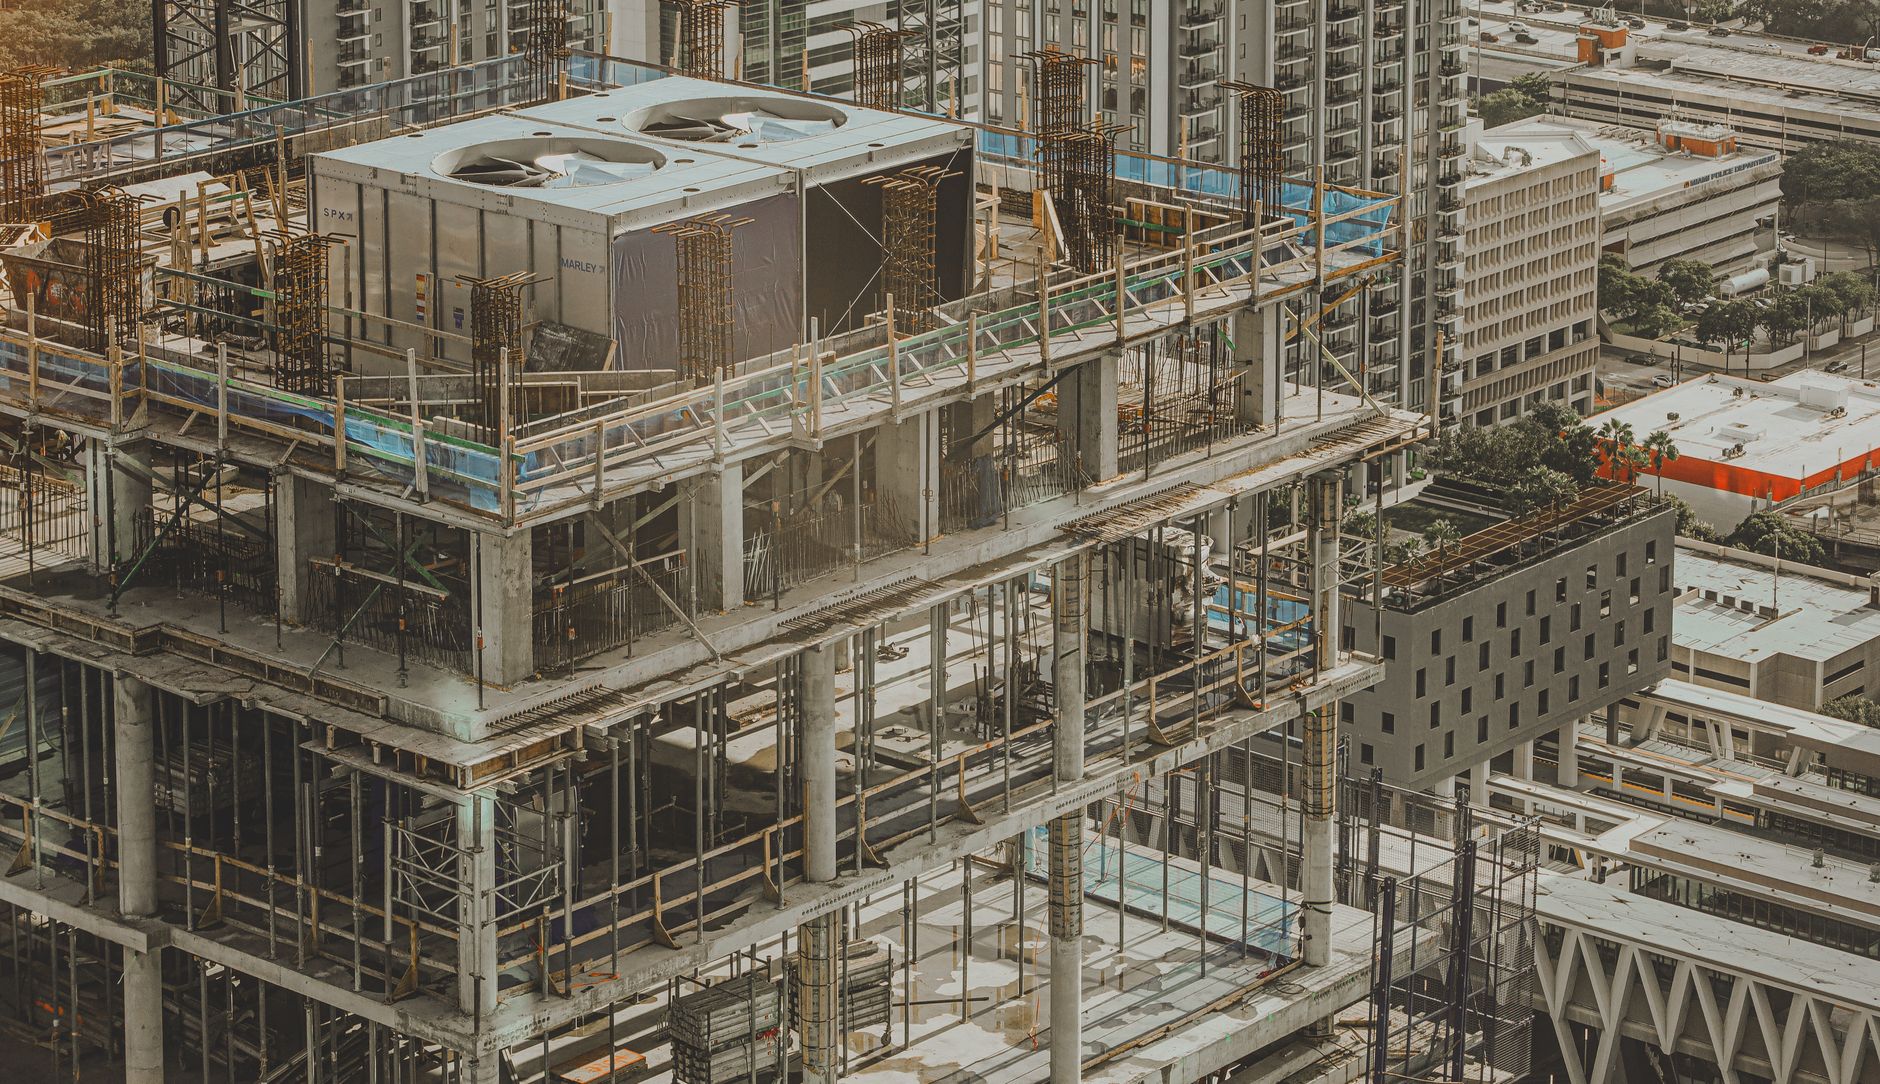
If a developer defaults on an off-plan project in Thailand, you face a straightforward but uncomfortable reality: there is no government-backed deposit protection scheme, no mandatory escrow for foreign buyers, and no automatic refund mechanism. Your recovery depends almost entirely on what your sale and purchase agreement (SPA) says, how creditworthy the developer is, and whether the project assets have already been mortgaged to a bank.
This guide explains the default risk in plain terms, maps out your legal options under Thai law, and shows you the contract clauses that make the difference between recovering your money and losing it.
Quick answer
- No deposit protection law exists for off-plan buyers in Thailand as of 2026. Your money goes directly to the developer, not into a protected account.
- Your SPA is your main protection. Clauses covering completion guarantees, delay penalties, refund conditions, and asset charges determine what you can recover.
- Developer insolvency in Thailand is handled under the Business Reorganization Act or the Bankruptcy Act. Foreign buyers rank as unsecured creditors in most cases, which means you are paid last.
- Construction financing banks often hold a mortgage over the project land. If the developer defaults on the construction loan, the bank's claim takes priority over yours.
- Indicative loss exposure: in a typical Thai off-plan schedule, a buyer may have paid 30-50% of the purchase price before the first structural milestone is reached. That is the capital at risk if the developer stops work at that point.
- Assignment (selling your contract before handover) is a legal exit path in some SPAs but requires developer consent and carries its own costs, typically 2-5% transfer or assignment fees per market practice as of 2026.
Options and scenarios
Scenario 1: Developer delays but does not collapse
This is the most common problem. Construction runs 6-18 months behind the contracted date. The developer is still operating but slow.
What you can do depends on your SPA. A well-drafted contract includes:
- A delay penalty clause: the developer pays you a daily or monthly compensation, often set at 0.01-0.1% of the purchase price per day (indicative market range). This rarely appears in standard developer contracts unless you negotiate it in.
- A long-stop date: a fixed date after which you have the right to cancel and claim a full refund. Without a long-stop date, you may be stuck waiting indefinitely.
- A completion guarantee: a formal commitment, sometimes backed by the developer's parent company or a bank letter of support, that the project will finish.
If the delay clause is absent, your lawyer must argue breach of contract under the Thai Civil and Commercial Code, specifically the provisions on hire-of-work contracts (jang tham), which govern construction obligations. Courts can order refunds plus statutory interest at 7.5% per year under Thai law, but litigation takes 2-5 years.
Scenario 2: Developer suspends construction
The developer pauses work for months with no clear restart date. This sits between delay and default.
Your first step is to issue a formal written notice (by registered mail and email) demanding a restart timeline. This notice starts the clock on legal remedies. Under the Thai Civil and Commercial Code, a creditor who gives notice and receives no satisfactory response has grounds to terminate the contract and sue for damages.
Practically, you should:
- Commission a title search (obtainable from the Land Department) to check whether the project land carries a mortgage. If it does, the bank's claim ranks above yours in any forced sale.
- Obtain a copy of the Environmental Impact Assessment (EIA) approval and construction permit to confirm the project was legal. Illegal projects cannot be completed and give you stronger grounds to rescind.
- Engage a Thai lawyer immediately. Once other buyers start filing claims, the queue at the court matters.
Scenario 3: Developer enters formal insolvency
This is the worst case. The developer files for bankruptcy or a court-ordered business reorganization under Thai law.
Business Reorganization Act (1998, as amended): A court appoints a plan administrator. Construction may resume under a reorganized entity. Buyers' claims are listed but payment depends on the reorganization plan, which must be approved by a creditor vote. Foreign buyers can vote but typically hold little collective influence.
Bankruptcy Act (1940, as amended): The developer's assets are liquidated. Secured creditors (the construction bank with a mortgage) are paid first. Preferential creditors (employees, tax authority) follow. Unsecured creditors, including most off-plan buyers, share what remains, which is often very little.
In practice, buyers who paid by bank transfer in Thai baht and hold a properly registered SPA at the Land Department have a marginally stronger position than those with unregistered agreements, because registration creates a public record of the obligation.
Scenario 4: Assignment as an exit before default becomes formal
If you sense financial trouble early, selling your contract (assignment) before the developer formally defaults is the cleanest exit.
Assignment means you transfer your rights and obligations under the SPA to a new buyer. Key points:
- Most Thai developer contracts require written developer consent for assignment. Some prohibit it entirely in the first 1-2 years.
- Assignment fees charged by developers typically run 2-5% of the contract value (indicative, as of 2026), but this varies widely.
- You sell at whatever price the market will pay. If the project has problems, you will likely sell below what you paid.
- Assignment closes your exposure. Even a loss is often better than waiting through a multi-year insolvency process.
The off-plan discount versus the risk you carry
Developers market off-plan units at a discount to incentivize early commitment. As of 2026, the indicative off-plan discount in Thailand's main markets is 10-25% below comparable completed resale stock (market estimates; actual figures vary by location, developer tier, and project stage).
Here is a simple example using indicative numbers:
- Completed resale unit: 5,000,000 THB
- Same-spec off-plan unit: 4,000,000 THB (20% discount)
- Discount value: 1,000,000 THB
- Amount paid at contract signing (typically 20-30%): 800,000-1,200,000 THB
- If the developer defaults after signing and before the first milestone, you have risked 800,000-1,200,000 THB to save 1,000,000 THB
The math only works if the developer completes. The discount is not free money. It is compensation for the construction risk you absorb by paying early.
Typical staged payment schedule (indicative, 2026)
Most Thai off-plan contracts follow a milestone-linked schedule. A representative structure looks like this:
- Reservation fee: 1-3% at booking (often non-refundable)
- Contract signing: 10-20% within 30-60 days of reservation
- Foundation / piling complete: 5-10%
- Structure complete (floor by floor or full frame): 10-20% in 1-3 tranches
- Building shell / windows / roof: 5-10%
- Interior fit-out / MEP (mechanical, electrical, plumbing): 5-10%
- Handover: remaining balance, often 20-30%, plus transfer taxes
A buyer at the 'structure complete' stage has typically paid 40-60% of the purchase price. That is the capital at risk if the project fails at that point.
Comparison table
| Factor | Strong SPA (well-negotiated) | Standard developer SPA | No registered SPA |
|---|---|---|---|
| Refund right on default | Explicit, with timeline | Vague or absent | Absent |
| Delay penalty | 0.01-0.1%/day (indicative) | Absent in most cases | Absent |
| Long-stop date | Defined in contract | Often absent | Absent |
| Completion guarantee | Bank letter or parent guarantee | Developer promise only | None |
| Assignment allowed | Yes, with fee (2-5% indicative) | Often restricted | Not applicable |
| Creditor rank in insolvency | Unsecured (weak) | Unsecured (weak) | Weakest |
| Land registration of obligation | Registered at Land Dept | Usually not registered | Not registered |
| Recovery chance on developer default | Moderate (litigation path exists) | Low to moderate | Very low |
| Litigation timeline if needed | 2-5 years (Thai civil court) | 2-5 years | Longer, harder |
Risks and mistakes
Relying on verbal promises. Thai courts apply written contracts. Side letters or sales agent assurances about refunds, guaranteed returns, or completion dates are unenforceable unless they appear in the signed SPA or a registered addendum.
Signing the developer's standard SPA without review. Developer-drafted contracts are written to protect the developer. Clauses that say 'the company reserves the right to modify the construction schedule' effectively remove your delay remedy. A Thai lawyer's review costs 15,000-50,000 THB (indicative, 2026) and is the most cost-effective insurance you can buy.
Not checking the land title before paying. The land should carry a chanote (full title deed, formally called Nor Sor 4 Jor) - the highest grade of Thai title, registered at the Land Department. Lower grades (Nor Sor 3, Nor Sor 3 Gor) signal potential boundary and ownership disputes. Check for encumbrances, meaning mortgages held by construction lenders.
Paying large sums before the SPA is signed. Reservation fees of 1-3% are standard and acceptable. Paying 10-20% before the SPA is signed and reviewed gives the developer your money with zero contractual protection.
Assuming the project bank guarantees your payment. The construction lender finances the developer, not you. If the developer defaults on the construction loan, the bank can foreclose on the project land. Your claim against the developer still exists, but the asset backing it may be gone.
Ignoring early warning signs. Repeated construction schedule updates, delayed responses to queries, sales office closures, and developer social media going quiet are observable signals. Acting early - through assignment or legal notice - preserves more options than waiting.
Skipping title search updates. A title search done at booking may not reflect a mortgage registered three months later. Run a fresh search before each major payment tranche.
Not understanding the condominium juristic person. Once a condominium project is registered under the Condominium Act, a juristic person (a legal management entity for the building) is established. If the project stalls before registration, this entity does not exist and there is no collective body to represent buyers' interests.
FAQ
What legal rights do I have if my Thai developer defaults?
Your primary rights come from your sale and purchase agreement and from the Thai Civil and Commercial Code. If the SPA includes a refund clause tied to default or a long-stop date, you can terminate and sue for the amounts paid plus interest at the statutory rate of 7.5% per year. Without these clauses, you must argue breach of contract, which requires proving the developer failed to meet an obligation. Both paths lead to civil litigation, which typically takes 2-5 years in Thai courts.
Is my deposit protected by law in Thailand?
No. As of 2026, Thailand has no mandatory deposit protection law for off-plan property buyers. Your deposit goes directly to the developer. Protection comes only from contract terms and the developer's financial health, not from any government scheme or protected account.
Can I get my money back if the developer goes bankrupt?
It is possible but rarely straightforward. In bankruptcy proceedings, you rank as an unsecured creditor. Secured creditors (typically the construction bank holding a mortgage over the project land) are paid first. Preferential creditors follow. Unsecured buyers share what remains. In many Thai developer insolvencies, unsecured creditors recover a small fraction of their claims, if anything.
What is assignment and should I use it as an exit?
Assignment means selling your contractual rights to another buyer before the project completes. If you detect financial trouble early, assignment lets you exit with a partial loss rather than waiting through insolvency. Most Thai SPAs require written developer consent for assignment and charge a fee of 2-5% of the contract value (indicative, 2026). Check your contract before assuming assignment is available.
How do I check if the project land has a mortgage on it?
Visit or instruct a lawyer to visit the Land Department (Samnak Ngan Thi Din) with the land title number. The Land Department holds public records of all registered encumbrances, including mortgages. A mortgage in favor of a bank means that bank's claim ranks above yours if the developer defaults.
What contract clauses reduce my risk most?
The four most important clauses are: (1) a defined long-stop completion date with your right to cancel and receive a full refund if missed; (2) a daily or monthly delay penalty; (3) a completion guarantee from the developer's parent company or a bank; and (4) a clear refund mechanism specifying how and when returned funds are paid, including currency and timeline.
Does registering my SPA at the Land Department help?
Registering a sale agreement or promise-to-sell at the Land Department creates a public encumbrance on the land title. This does not guarantee recovery but it establishes priority over later unregistered claims and makes it harder for the developer to sell the unit to a third party. It is not common practice for condominiums but is worth discussing with your lawyer.
What is the difference between delay and default?
Delay means the developer is still working but behind schedule. Default typically means the developer has stopped performing its obligations entirely, either by halting construction, missing a formal obligation, or entering insolvency. The legal remedies differ. Delay triggers penalty and long-stop clauses. Default triggers termination and refund rights, plus potential insolvency proceedings if the developer cannot pay.
Should I buy from a developer listed on the Stock Exchange of Thailand?
Listed developers (those whose shares trade on the Stock Exchange of Thailand) are subject to disclosure requirements and regulatory oversight that private companies are not. Their financial statements are public, which lets you assess their debt levels and project pipeline before buying. This does not eliminate default risk, but it gives you more information to assess it. As of 2026, several of Thailand's largest condominium developers are listed companies.
How much of my money is typically at risk before construction is complete?
Using a standard Thai staged payment schedule, you will typically have paid 40-60% of the purchase price by the time the building structure is complete. At handover, the remaining 20-30% is due. The period of highest relative risk is between contract signing and the structural completion milestone, when your payments are largest and the physical asset you can claim against is least developed.
Planning a property purchase in Thailand? Send us your requirements - the THAI.ESTATE team will reply with specific options and a safety checklist for your case.